$XRP registered an intraday high of $1.60 on Sept. 22, with roughly $7.4 billion in reported volume. The move was strong, but the latest public data on regulated futures showed different positioning shifts across venues.
The Commodity Futures Trading Commission's Sept. 15 snapshot showed leveraged funds cutting their net short in CME futures by the equivalent of 46.3 million $XRP in one week. Net short means reported short contracts exceeded reported long contracts.
Across three separately reported Coinbase Derivatives products, adjusted for each contract's unit, the same trader category reduced its combined net short by only 2.452 million $XRP and remained short about 141.6 million $XRP.
That disconnect points to a concentrated positioning reset. The dates also block a causal conclusion: the positions were observed Sept. 15 and released Sept. 18, before the Sept. 22 price snapshot.
CME's reset dwarfed the Coinbase shift
CME's standard future represents 50,000 $XRP per contract. Leveraged funds held 1,585 long contracts and 2,304 short contracts on Sept. 15, leaving a 719-contract net short equal to 35.95 million $XRP.
A week earlier, their reported position was 1,280 longs against 2,925 shorts, or 1,645 contracts net short, equivalent to 82.25 million $XRP. The change between reports reduced the net short by 926 contracts, or 46.3 million $XRP.
The shift came from both higher longs and lower shorts. Leveraged-fund longs rose by 305 contracts while shorts fell by 621. Short reductions drove most of the improvement, but some new long exposure also appeared.
Open interest fell by 509 contracts over the same week, equal to 25.45 million $XRP. The decline is compatible with traders closing positions even as the category added longs.
Coinbase posted a smaller change after converting its three reported products into $XRP-equivalent amounts. The standard Coinbase future represents 10,000 $XRP per contract. The products labeled NANO $XRP and NANO $XRP PERP STYLE in the CFTC table each represent 500 $XRP per contract.
Reported market Sept. 8 leveraged-fund net short $XRP Sept. 15 leveraged-fund net short $XRP Weekly change CME, 50,000 $XRP per contract 82.25 million 35.95 million 46.30 million $XRP less short Coinbase standard, 10,000 $XRP per contract 132.17 million 128.52 million 3.65 million $XRP less short Coinbase nano, 500 $XRP per contract 0.9945 million 0.9025 million 0.092 million $XRP less short Coinbase nano perpetual-style, 500 $XRP per contract 10.902 million 12.192 million 1.290 million $XRP more short Coinbase three-product total 144.0665 million 141.6145 million 2.452 million $XRP less short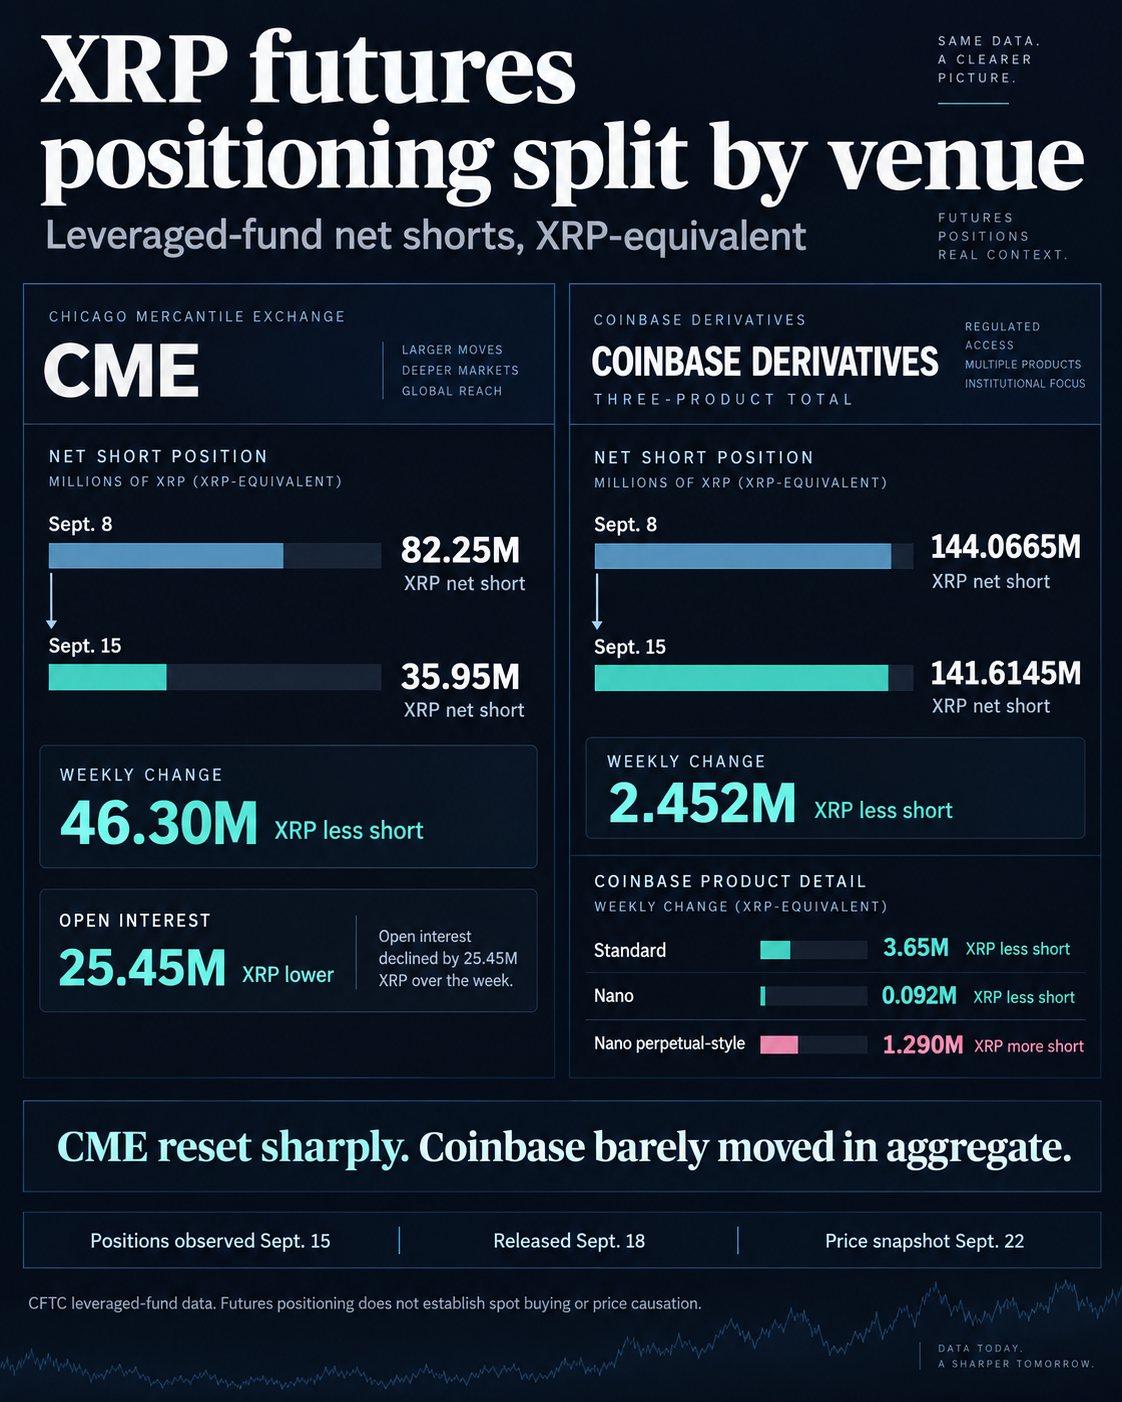
The standard contract accounted for most of Coinbase's modest improvement, while the nano contract contributed another 92,000 $XRP. The perpetual-style contract went the opposite way: leveraged funds became 1.29 million $XRP more net short.
That increase offset part of the reduction in the other two products. The resulting Coinbase aggregate was still nearly four times the CME net short on Sept. 15 and had moved only a fraction as much over the week.
The Coinbase perpetual-style product is structurally distinct from the unexpiring swaps common on offshore exchanges. It is a regulated, five-year cash-settled future that uses funding adjustments. Its positioning can reflect a different mix of participants and strategies, which is one reason the separate product rows matter.
CME changed far more than Coinbase overall, and Coinbase's products moved in opposing directions. The combined evidence offers weak support for a market-wide directional turn.
What the $XRP positioning can and cannot show
The CFTC's leveraged-funds category covers traders whose predominant self-reported business activity fits that classification. The report also has a separate field for mechanical spreading positions, but neither feature establishes the motive behind every long or short.
A short position can express a bearish view, hedge spot exposure, offset another derivative or form one side of a basis trade. Reducing it can reflect a bullish change, a hedge adjustment, a relative-value unwind or a broader cut in risk. Public aggregates leave individual firms and each contract's economic purpose unidentified.
Those limits are key because the headline CME move combines rising longs, falling shorts and lower total open interest. The supported conclusion is that leveraged-fund positioning on CME became much less short. Labeling the full change as fresh directional buying, or as the cause of $XRP's later gain, would exceed the evidence.
The comparison is also limited to the four contract families in the dated CFTC query, since CME lists Micro $XRP as a distinct product. Under CFTC rules, a market is included in Commitments of Traders reports only when at least 20 traders hold positions at or above reporting levels.
A missing row leaves activity in another product unknown, and the reporting threshold is only a possible explanation for a specific absence.
The reporting lag now provides the next test. CFTC reports generally reflect Tuesday positions and are usually released Friday at 3:30 p.m. Eastern time. The agency's tentative 2026 schedule lists Sept. 25 for the report normally covering Sept. 22.
That snapshot can show whether the cross-venue split persisted during the rally, while price causation remains outside what weekly positioning data can resolve.
A broader directional shift would gain support if Coinbase's combined net short also fell materially, particularly alongside expanding open interest. If Coinbase remains heavily short while CME stays much less short, the data would continue to favor a venue-specific reset.
For now, three observations can stand together without being forced into one causal story: $XRP rallied, CME leveraged funds had already reduced a large net short, and comparable Coinbase positioning had barely changed in aggregate.
The divergence is the signal, while the reason behind it remains outside what weekly category data can establish.