The cryptocurrency market is entering the fourth quarter (Q4) amid expectations of a traditional rally known as "Uptober." Investors are counting on an immediate surge across all major crypto assets, but Ripple's "North Star," $XRP, appears set to follow its own path.
Historical metrics by CryptoRank and the current technical picture on TradingView charts point to a paradox: the best Q3 close in four years may not save the bulls from a prolonged pause in October.
What's wrong with expectations for an $XRP in "Uptober"?
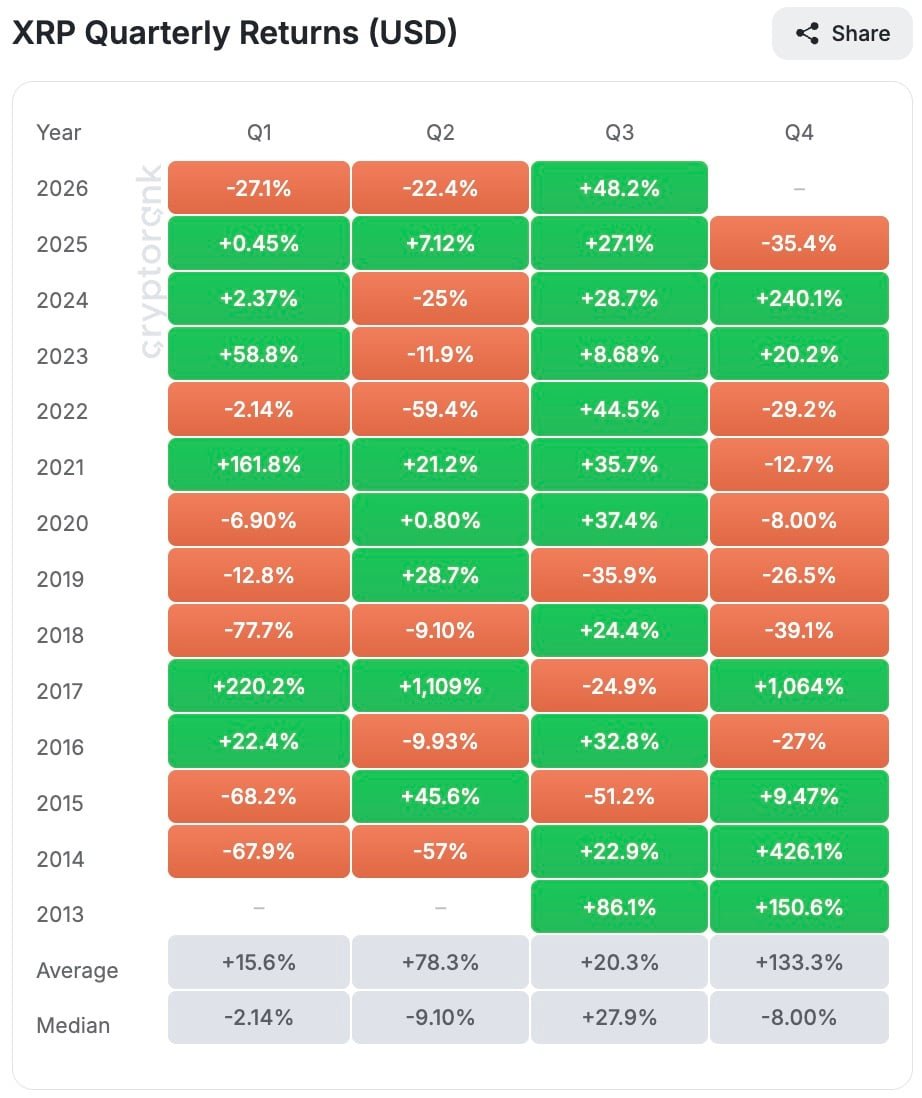
The market's main catalyst was a strong third-quarter close. Amid a large influx of capital into U.S. spot ETFs, the token posted a return of +48.1%, its best Q3 performance since 2022. $XRP settled at $1.54, fully erasing its first-half losses and flashing a bullish signal on the weekly timeframe.
However, that rapid surge also created local overbought conditions, which could leave the bulls stuck in consolidation. September's rally was driven in large part by a short squeeze, or the forced closure of short positions.
The futures market is now overloaded with leverage. For the uptrend to continue in a healthy way, the price needs a technical pullback and a retest of support in the 1.30–1.40 range. October is an ideal time for that reset.
Data from CryptoRank clearly shows why bulls should not expect the rally to continue immediately: October has historically been $XRP's worst month of the year. Its average return for the month is -5.14%, while the median is -2.97%.
$XRP has consistently ended October lower in past cycles, including in 2024 and 2025.
At the same time, the average return for the entire fourth quarter looks impressive at +133.3%. The reason is that most liquidity enters the market with a delay, leaving the quarter's median return in negative territory at -8.00%.
The main phase of capital deployment has historically come in late autumn: November leads with a median return of +80.2%, while December maintains a strong +63.1%.
$XRP is on the threshold of a strong bull cycle, but technical factors rule out an immediate acceleration at the start of the quarter. October will likely bring an extended sideways trend or a moderate correction.