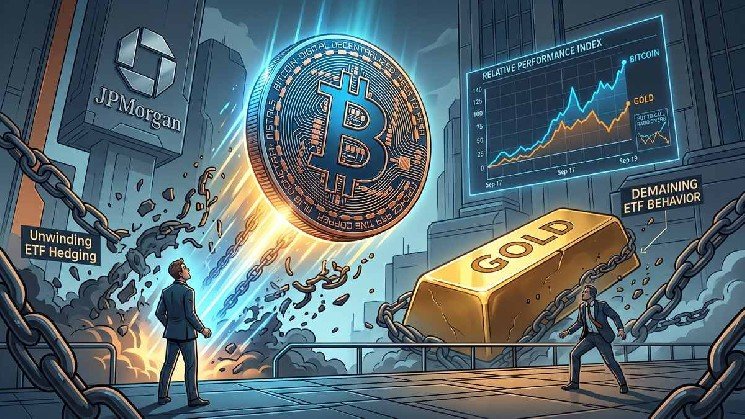
- Gold exchange-traded funds recouped 100% of their cumulative capital outflows during 2026, whereas spot Bitcoin ETFs recovered approximately 50%.
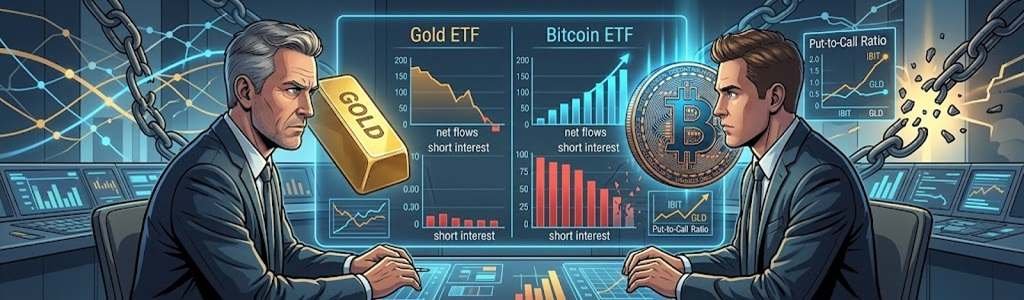
- Short interest on BlackRock’s iShares Bitcoin Trust (IBIT) is trading near its highest levels recorded during 2026.
- The put-to-call open interest ratio on IBIT options remains above the historical average of equivalent instruments such as the SPDR Gold Shares (GLD).
Financial firm JPMorgan anticipates that in the coming months Bitcoin will outperform gold in relative performance if institutional investors begin unwinding their defensive hedges in exchange-traded funds, according to a report published on Thursday, September 17, 2026.
INTEL: JPMorgan says Bitcoin could gain more support than gold as ETF hedging eases
— Solid Intel 📡 (@solidintel_x) September 17, 2026
Analysts from the entity pointed out that institutional exposure across both assets increased following the Federal Reserve’s July meeting. Nonetheless, the behavior of derivatives positions reflects a marked disparity between both markets.
Net flows into exchange-traded vehicles indicate that gold has led institutional recovery throughout the year. According to the JPMorgan report, recent inflows into ETFs tied to the precious metal erased all prior capital losses from 2026. Meanwhile, Bitcoin-backed instruments have only offset half of the redemptions incurred over the same period.
Despite this gap in net flow figures, JPMorgan analysts argue that the underlying derivatives metrics present a different scenario. According to data from the team led by Nikolaos Panigirtzoglou, crypto market participants maintain elevated levels of downside protection through options contracts.
Short interest registered on BlackRock’s IBIT fund remains near its annual ceiling in September 2026. In contrast, short interest on the SPDR Gold Shares (GLD) ETF currently sits below its historical average. This divergence confirms that institutional traders are assigning a decidedly defensive bias toward the cryptocurrency relative to the yellow metal.
Options market data reinforces this statistical asymmetry. The put-to-call ratio on IBIT demonstrates higher demand for put contracts to protect spot positions. According to the financial firm’s analysis, an easing of these hedges could unleash outright spot buying and upward pressure on the relative price of Bitcoin against gold.
Disparity in Institutional Hedges and Regulatory Factors
The bank’s stance has evolved gradually throughout the current financial year. In early February 2026, the firm estimated the average production cost of Bitcoin at $77,000, after kicking off the annual cycle at $90,000.
Later, in June 2026, analysts observed that the market price lingered for five consecutive months below this estimated extraction cost. According to JPMorgan’s long-term volatility-adjusted projections, the theoretical valuation of the cryptocurrency stands at $266,000 when benchmarked against the global volume of gold.
The macroeconomic landscape and legislative uncertainty in the United States continue to sway portfolio allocations. The bank warned during the summer of 2026 regarding narrowing legislative windows for advancing the Clarity Act in the U.S. Congress.
Trading desks are keeping a close watch on the end of the third quarter of 2026 and the upcoming Federal Open Market Committee (FOMC) monetary policy meeting scheduled for late this month as the immediate catalysts for a potential restructuring of hedges.